All Categories
Featured

2026 Term Life Insurance Rates for Families
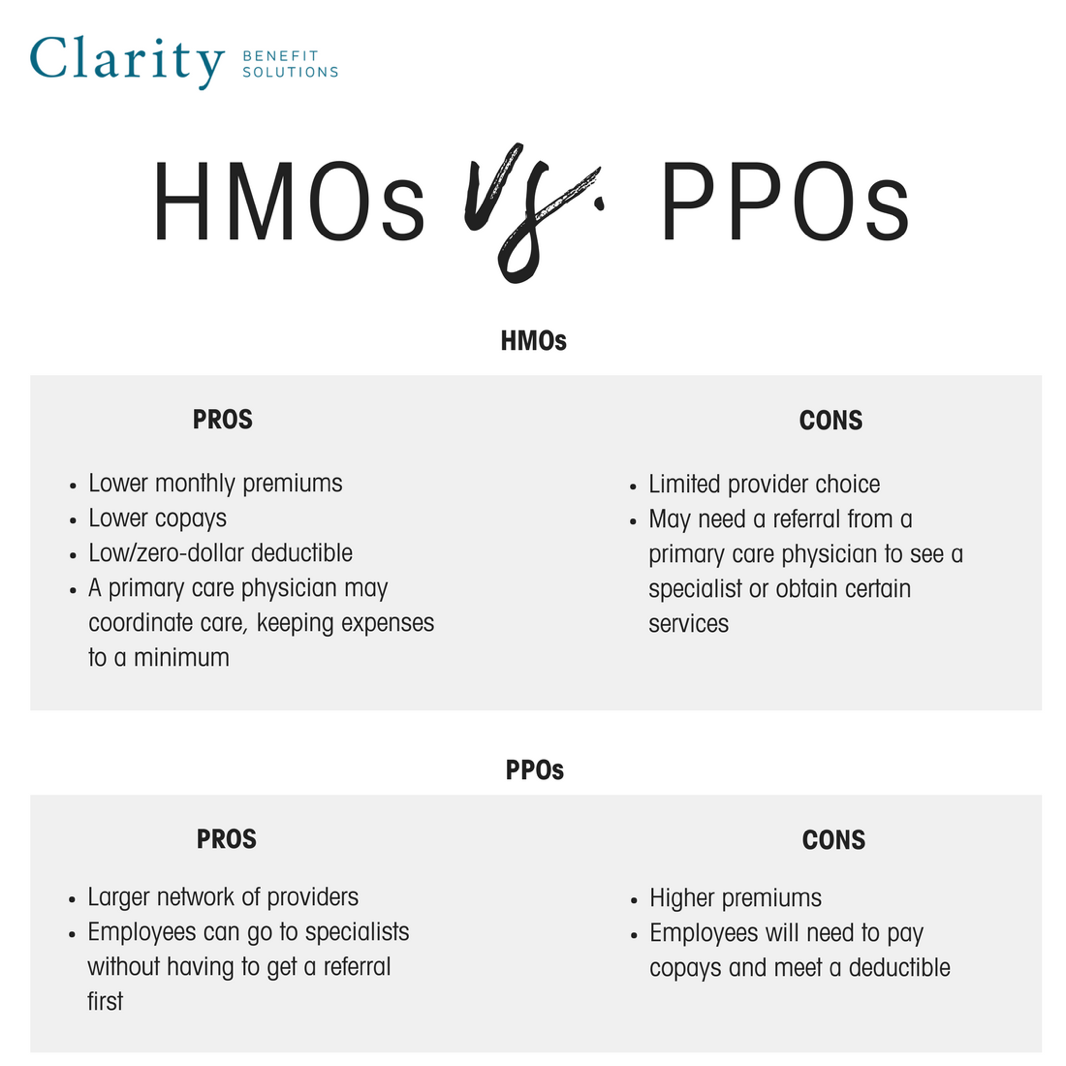
An HMO insurance plan is typically considered being more cost-efficient due to its lower regular monthly premiums and practical due to its requirement that patients must have a medical care physician to handle their care. A PPO insurance coverage plan is understood for its flexibility as it permits patients to handle their own care and seek out various providers/specialists without needing a recommendation.
Comparable to general insurance coverage strategies, the 2 primary Medicare Advantage strategies are HMO and PPO.While HMO and PPO insurance prepares continue to be the most typical choice for clients to select from, there are a variety of other insurance coverage alternatives. HMO and PPO insurance coverage plans are the 2 most common health care insurance coverage plans in the United States.
While these insurance strategies are different, they are comparable in the sense that they supply a patient with a network of medical professionals, medical facilities, and other doctor that help members with their health-care journey. "HMO" functions as an acronym for "Health care Organization," while "PPO" works as an acronym for "Preferred Service Provider Organization." An HMO insurance plan is centered around a variety of health centers and healthcare providers (described as an "HMO network") that have actually accepted deal with clients within the network's insurance coverage strategy. A referral is necessary for a patient to see other specialists that are in-network or out-of-network, and frequently, receiving out-of-network care just happens in emergency situation circumstances. This strategy offers lower month-to-month premiums for its customers, making it an affordable insurance option. Low month-to-month premiums. Not as numerous claims to submit due to in-network care.
Often, lower costs for prescriptions. A client can only see service providers within the strategy's network unless they have a referral for an outdoors specialist, or it's an emergency scenario.
Evaluating PPO vs HMO Insurance
This plan likewise lets the patient coordinate their care and manage which service providers they want to see, versus having a primary care doctor. The client has more flexibility with which suppliers they choose to see, whether they're within the plan's network or out-of-network. Most times, there is no need for a referral if a patient cares to see an out-of-network specialist.
The client is responsible for handling their healthcare, vice a main care physician supervising. A 'service provider network' refers to the list of medical professionals, specialists, healthcare facilities, etc that an insurance agency contracts to supply medical services to its strategy members. Service providers that are 'in-network' refer to the health care workers and hospitals that are listed in the plan.
The expenses associated with an HMO plan include deductibles, which is the quantity a patient must pay before insurance coverage contributions, and regular monthly premiums, which is the amount gotten of a patient's paycheck. Typically, the monthly premiums gotten with an HMO plan are lower than a PPO strategy's premiums.

Every year, this caused a $6,869 coverage on people and $19,445 protection on households, showing a lower monthly premium in contrast to a PPO plan type. Deductibles, monthly premiums, and copays are expenses frequently associated with a PPO plan. The majority of times, the regular monthly premiums are taken out with a PPO plan that is more costly than an HMO strategy's premiums.
Evaluating PPO and HMO Health Plans
According to the Kaiser Family Foundation 2018 Health Benefits Study, all companies utilizing a PPO insurance strategy paid $592 as the month-to-month premium on a private and $1,694 as the month-to-month premium on a household. Yearly, this resulted in a $7,149 protection on individuals and $20,324 protection on families, revealing a greater regular monthly premium in comparison to an HMO plan type.
When trying to decide which strategy is best, there are many factors to think about, with some of the most important being flexibility, cost performance, and coordination of care. If it's flexibility that is most important, then a PPO insurance strategy might be a better suitable for they permit a patient to have more control over which suppliers they see and when, despite a referral.
Another benefit to an HMO plan is that it requires a patient to have a primary care physician that collaborates their look after them. This implies that with a PPO insurance strategy, the client will have to manage their own care and manage which providers/specialists they require to visit. In the end, one plan is not considered better than the other.
Medical insurance strategies do not cover dental insurance coverage. For more information on acquiring an oral plan, such as a dental HMO strategy, 'DHMO strategy,' or an oral PPO plan, 'DPPO plan,' visit this resource. When an American (who has actually been paying Medicare taxes for a minimum of ten years) turns 65, they get approved for the medical insurance plan called Medicare.

Latest Posts

Reviewing Medigap Options for Maximum Coverage

Exploring How Whole Life Insurance Works

Building Long-Term Security Through Life Insurance